
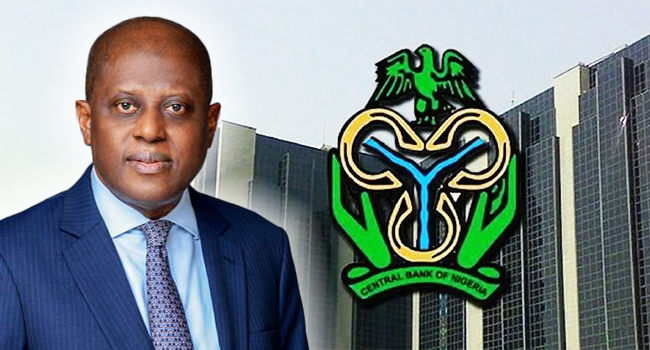
The Central Bank of Nigeria (CBN), has intensified its regulatory crackdown on loan defaults by blacklisting top defaulters and restricting their access to banking services.
This decisive move targets “chronic defaulters” and large-ticket obligors—individuals and corporations with substantial non-performing loans (NPLs)—and signals a major shift toward financial discipline, accountability, and systemic stability in Nigeria’s banking sector.
Background and Policy Context
For years, Nigeria’s financial system has struggled with rising non-performing loans, particularly among:
- High-net-worth individuals
- Large corporations with multi-billion-naira exposures
These borrowers often exploited regulatory gaps, including:
- Loan restructuring under regulatory forbearance
- “Credit jumping” (moving between banks to secure fresh loans despite existing defaults)
With the expiration of forbearance policies, the true scale of bad loans became visible, prompting urgent regulatory intervention.
Policy Announcement and Key Players
a. Leadership and Announcement
The policy was formally reinforced following remarks by Olayemi Cardoso, Governor of the CBN, at the:
- 4th Annual IMF/AFRITAC West 2 High-Level Executive Forum held in Abuja
Cardoso emphasized that:
“The era of regulatory forbearance for delinquent borrowers is over.”
b. Institutional Framework
The enforcement mechanism relies on:
- The Credit Risk Management System (CRMS)
- Licensed private credit bureaus
- Regulatory backing under BOFIA 2020
Key Features of the Blacklisting Policy
a. Restriction of Banking Services
Affected borrowers are now barred from accessing:
- New loans and credit facilities
- Letters of credit
- Performance bonds
- Bank guarantees
This represents a broad financial exclusion, not just a credit restriction.
b. Target Group: Large-Ticket Obligors
The directive focuses on:
- Borrowers with non-performing loans (over 90 days overdue)
- Entities with significant systemic financial exposure
These defaulters are flagged across all banks, effectively blacklisting them from the entire financial system.
c. End of Regulatory Forbearance
The CBN has:
- Terminated leniency previously granted to delinquent borrowers
- Tightened supervision and compliance standards
- Reinforced strict loan classification rules
d. Protection of Banking Sector Capital
A major motivation is safeguarding the ₦4.61 trillion in new capital recently raised by Nigerian banks.
Cardoso stressed:
“Our stance on corporate governance is unequivocal: zero tolerance for violations.”
Strategic Objectives of the Policy
a. Enforcing Credit Discipline
The policy aims to instill a “culture of repayment”, especially among elite borrowers who historically defaulted without consequences.
b. Safeguarding Financial Stability
By restricting chronic defaulters, the CBN seeks to:
- Protect depositors’ funds
- Reduce systemic risk
- Strengthen bank balance sheets
c. Eliminating “Credit Jumping”
The directive prevents defaulters from:
- Switching banks to access new loans
- Accumulating unsustainable debt across institutions
d. Strengthening Corporate Governance
The policy reinforces:
- Accountability among borrowers
- Compliance within financial institutions
- Transparency in credit allocation
e. Aligning with Monetary Policy Reforms
The crackdown is part of a broader shift toward orthodox monetary policy, which prioritises:
- Price stability
- Inflation control
- Policy credibility
This marks a move away from interventionist lending practices toward core central banking functions.
Implications of the Policy
a. For Borrowers
- Severe restriction of financial operations
- Limited access to trade finance instruments
- Increased pressure to repay outstanding debts
b. For Banks
- Improved asset quality
- Lower exposure to bad loans
- Stronger risk management frameworks
c. For the Economy
Positive Outcomes:
- Enhanced financial system stability
- Increased investor confidence
- Better allocation of credit
Potential Downsides:
- Liquidity constraints for large firms
- Short-term slowdown in credit-dependent sectors
Link to Broader Economic Reforms
The blacklisting policy is part of a wider reform agenda under the current CBN leadership, including:
- Banking sector recapitalisation
- Strengthened regulatory oversight
- Reduced reliance on direct intervention programs
The shift toward orthodox policy signals a return to global best practices in central banking.
Challenges and Criticisms
a. Economic Impact on Large Corporations
Some stakeholders fear:
- Operational disruptions
- Reduced access to trade finance
- Potential job losses in affected sectors
b. Enforcement Complexity
- Requires coordination across all banks
- Depends heavily on accurate credit reporting systems
c. Credit Tightening Risks
- Stricter lending conditions may reduce overall credit flow
- Could impact economic growth in the short term
Conclusion
The CBN’s decision to blacklist top loan defaulters and restrict banking services represents a turning point in Nigeria’s financial regulation.
By ending regulatory forbearance and adopting a zero-tolerance stance, the apex bank aims to:
- Enforce accountability among borrowers
- Protect the integrity of the banking system
- Promote sustainable financial practices
While the policy may create short-term disruptions, it is a critical step toward long-term financial stability and economic resilience in Nigeria.
Recommendations
- Strengthen credit monitoring systems for real-time tracking
- Encourage structured loan restructuring for viable firms
- Improve transparency in lending practices
- Promote financial literacy on debt management
- Ensure phased enforcement to minimise economic shocks
